
Interview and text by Masayuki Hirota (Chronos-Japan)
[First published in the November 2016 issue of Kronos Japan]
Japanese watchmakers have seen a rapid improvement in their performance in recent years. Some say this is thanks to inbound demand, but it's also fair to say that the steady efforts they've made since the so-called "Lehman Shock" are starting to bear fruit. Seiko, Citizen, and Casio are now entering a growth phase. Let's take a look at the current situation and future strategies of these three major Japanese watchmakers.
Overview of Japanese watchmakers / The watch market environment and trends among domestic and international manufacturers
Seiko, Citizen, and Casio, three of Japan's leading domestic watchmakers, have drawn up next-generation strategies with an eye on the world. Before delving into the details, we will first provide an overview of the current state of the watch market and the trends of domestic and international watchmakers/brands in order to understand the situation these three companies find themselves in. Please keep this in mind as you continue reading this special feature.
Performance trends of Japan's three major watch companies
The three major Japanese watch manufacturers (Seiko, Citizen, and Casio) have all reportedly achieved record-high operating profits in the first half of fiscal year 2015 (April-September 2015) (Nikkei Shimbun, November 10, 2015). In reality, this refers to the period after Seiko and Citizen transitioned to holding companies, and their operating profits (profits from their core business) have not yet reached the levels of the early 1990s or mid-2000s for Citizen, nor the mid-1980s for Seiko, so it cannot necessarily be called a record-high profit. Nevertheless, it can be said that each company has overcome the downsizing and restructuring of its non-watch businesses and is on the verge of reaching record-high profit levels in the watch business.
The main factors behind the strong performance of the watch business include the improvement in global economic sentiment, rising income levels in emerging countries, particularly China, the depreciation of the yen and recovery of domestic demand since Abenomics, and demand from inbound tourists.
Looking at the sales trends of each company's watches, from fiscal year 2010, the year of the Great East Japan Earthquake, to fiscal year 2014, Seiko's sales increased from just over 1000 billion yen to just under 1600 billion yen, about 1.6 times, and Citizen's increased from just under 1400 billion yen to just over 1700 billion yen, about 1.25 times, showing generally upward growth. Casio does not disclose sales figures for watches alone, but in my estimation, it grew from around 900 billion yen to around 1500 billion yen, a 1.7-fold increase (Figure 1).
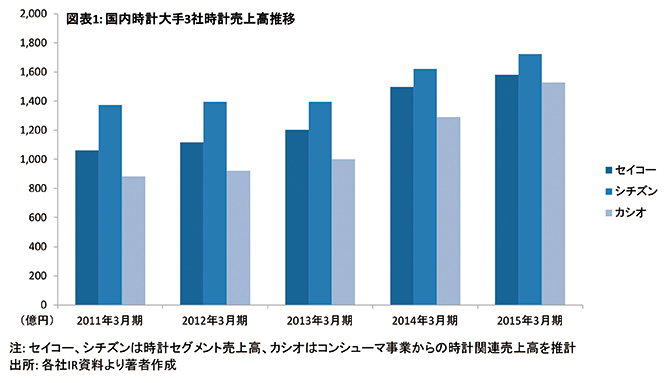
While each company discloses sales by region on a company-wide basis, they do not disclose sales for watches only. However, based on each company's regional sales on a company-wide basis and the size of the domestic watch market, if we assume that domestic sales account for around 3% and exports for around 7%, these figures would not be far off. The breakdown of export destinations seems to vary greatly depending on whether only finished products or movements are included, and while this is difficult to generalize, we can point to trends such as Casio's relatively high proportion of sales in emerging markets due to the popularity of G-Shock in Asia and the Middle East, and Citizen's high proportion of sales in North America when Bulova is included.
Domestic watch market
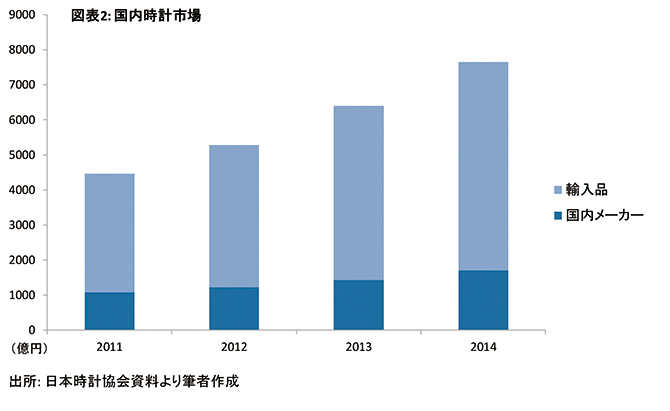
According to the Japan Clock & Watch Association, the domestic watch market in calendar year 2014 was worth 7649 billion yen, of which 1709 billion yen was for domestically manufactured products and 5940 billion yen for imported products (Figure 2). Looking at trends over the past few years, while the overall market has grown at an average annual rate of around 20% from a scale of around 5000 billion yen, the number of units sold has remained roughly flat, indicating that rising unit prices have been driving market expansion. The share of domestic manufacturers has remained stable at roughly 22-24%, and in an environment where imported products have risen in price due to price revisions caused by the weak yen, etc., it appears that domestically manufactured products have also seen an increase in unit prices. Roughly speaking, the average annual growth rate is just under 1% in volume and just under 1% in unit price.
For 2015, the figures are based on fiscal year rather than calendar year, so they do not necessarily align with the figures from the Watch Association, but all three companies saw domestic watch sales increase by around 30% compared to the previous year, indicating even faster growth than last year. Factors behind this include a rebound decline in the first half of 2014 following the consumption tax hike, which leveled out in 2015, as well as a further increase in inbound demand (increased number of travelers). Inbound demand tends to be particularly noticeable at mass retailers in large cities with many overseas tourists, so it would be useful to compare sales growth by region to distinguish between inbound and domestic demand.
Japanese manufacturers in the global market
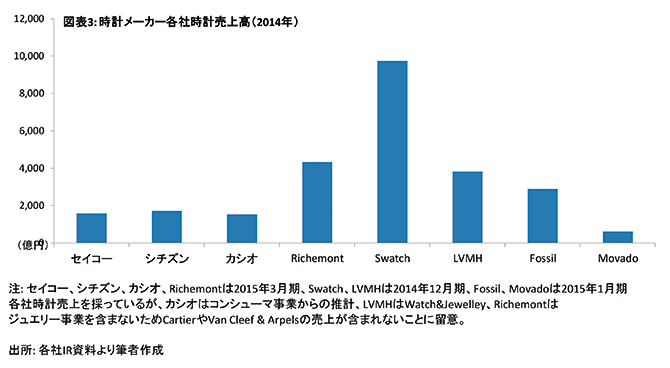
Meanwhile, estimates of the global market vary widely, with estimates ranging from ¥6 trillion to ¥8 trillion. Detailed data is difficult to obtain because well-known manufacturers such as Patek Philippe, Rolex, Breitling, and Franck Muller are unlisted and do not disclose financial or production data, but most studies place the market at around ¥6 trillion. The combined sales of the three domestic watch companies are approximately ¥480 billion, which represents less than 10% of total sales in any given case. While comparable in size to the Richemont Group's ¥430 billion watch division and the LVMH Group's ¥380 billion watch and jewelry division, it is roughly half the size of the Swatch Group's sales of just under ¥1 trillion. According to estimates from Forbes and Deloitte Touche Tohmatsu, Rolex's sales are estimated at ¥700 billion to ¥900 billion, exceeding the combined total of the three domestic watch companies. In terms of size and unit price, the Japanese manufacturers are competing with and comparing themselves to the Fossil Group and Movado Group (Figure 3).